
Elicio Therapeutics, Inc. ELTX
Set alert
At close · Oct 30
After hours · Oct 30, 7:57 PM ET
- YTD
- -78.89%
- 1 year
- -81.84%
- Open
- 1.74
- Prev close
- 1.75
- Mkt cap
- 45.51M
- Vol
- 183.88K
- Avg vol
- 313.34K
- EPS
- -2.16
- P/E
- 0.00
- Div yield
- 0.00%
More statistics
- Low
- 1.66
- High
- 1.78
- Forward P/E
- -1.96
- Beta
- 0.00
- Short ratio
- 2.49
- Inst. own
- 5.82%
- Dividend
- 0.00
- Ex-div date
- Earnings
- Aug 13, 2024
- 50-d avg
- 4.92
- 200-d avg
- 5.97
- 1y target
- 9.50
Discussion (9)
Sign in to join the discussion
 Khoopy ELTX 4 months ago #1
$ELTX The news is certainly not what everyone was hoping to get…
But it seems to me that everyone is throwing out the baby with the bath water. Their platform is working, and it’s demonstrating undeniable positive impact on an entire group patients with pancreatic cancer (almost doubling life expectancies). This group has zero medical treatment options to date.
In the long run, this is actually very good news. Though the target was missed, the study showed valuable unexpected impact in a different group, allowing the company to fine tune their phase 3. With zero toxicity concerns, this group can now receive the drug on a potentially ongoing basis and benefit from the extended life-expectancy. It’s hard to imagine that their phase 3 will not be successful. They have derisked the study, which is partly what phase 2 studies are designed to do.
Besides, the play will $ELTX has always been the platform, not a single drug. IMHO, this is more of a panic selling. And phase 2 is demonstrating beyond doubt that the platform works.
Here’s the link to a full report, with key point below.
- AMPLIFY-7P did not meet the pre-specified primary endpoint of disease-free survival ("DFS") in the intent-to-treat population.
- Randomization balanced most prognostic factors between arms. However, the ELI-002 7P arm had a higher proportion of R1 resected (higher residual disease, tumor present at or within 1 mm of surgical margin) patients compared with the observation arm (ELI-002 7P 19% vs. observation 10%), a known adverse prognostic factor for recurrence.
- R1 patients have increased relapse-risk, implying that this imbalance meaningfully and negatively impacted the ELI-002 arm.
- Post-hoc analysis identified a stronger DFS hazard ratio in the R0, completely resected population (post-hoc HR 0.65, p=0.048, ELI-002 7P mDFS 23.8 mo vs observation 12.8 mo, n=121). Absolute recurrence rates observed at 18 months were 9.5% lower for the ELI-002 7P arm.
- Lower residual disease (R0 completely resected) patients represented approximately 84% of the AMPLIFY-7P study, indicating potential for a significant population with high unmet need.
- Mutant KRAS ("mKRAS")-specific T cell responses strongly correlated with improved DFS, supporting biological activity of ELI-002 7P (HR 0.22, p<0.0001, n=90).
- Findings inform a refined Phase 3 development strategy focused on a defined R0 resected population and additional ELI-002 7P dosing, with the potential to address a significant unmet need and market opportunity in the adjuvant setting.
- The favorable safety and tolerability profile of ELI-002 7P supports the potential for longer-term administration and combination approaches.
- Elicio is evaluating multiple strategic financing and partnering opportunities to support future clinical development.
- Elicio will host a conference call today, Monday, June 15, 2026, at 8:30 AM ET.
Khoopy ELTX 5 months ago #2$ELTX Nice move today. I think people have started to take in the significance of the recent publication this week with mouse data on a new viral DNA linked to their Trojan horse carrier that increases the immune response drastically, basically acting as a turbo charger for their vaccine platform. Much better than the current peptide based adjuvant they’re using in the clinical trial. They also showed the mechanism of activation which is important. The paper was published in Science, which is one of the highest regarded scientific journals.
All of this shows that the value in $ELTX is not just in their current solution awaiting phase II results. It’s in the platform itself. And this puts $ELTX in an entirely different league from a company like $RVMD—their closest comp. $ELTX’s platform can generate a whole spectrum of vaccines targeting at a diverse range of diseases. Put plainly, they are demonstrating their potential to become a pharma with several many drugs—not just one solution to a limited range of diseases.
$RVMD is valued at ~$33B with their single solution. Today $ELTX is valued at ~$250M. Just do the back of the envelope math and you end up with 150x potential, just based on their current phase II agent alone—which already offers a better solution than RVMD’s bespoke vaccine therapy. Add in the potential for $ELTX’s platform and that 150x quickly proves a low multiple.
I think the run up in the last few days is lead by people who have started to see this math. Definite long here. This company will create generational wealth for those getting in at current valuations and holding for 2-3 years.
Khoopy ELTX 5 months ago #3$ELTX Q1 report shows nearly 1.3M shares sold by company ATM since Jan 1, 2026, with share prices remaining reasonably steady. More importantly, fewer disease progressions and deaths than projected to date have been observed in the ongoing 2:1 randomized Phase 2 AMPLIFY-7P trial.
So far, so good.
On pins and needles waiting for phase 2 results!
Khoopy ELTX 6 months ago #4$ELTX $RVMD If phase 2 results end up being what we all hope for, dilution will not be a major factor here. RVMD showed an increase life expectancy of ~6 months longer than placebo/chemo. This news + fda approval added ~$4-$5B to the company’s valuation overnight.
So far, ELTX has been showing an increase of ~ 18 months. And ELTX has a better mousetrap: an off the shelf vaccine that hits 7x more targets on the cancer tumor, with tests showing the development of still other tumor-fighting agents by the host’s own immune system that were not part of the vaccine’s targets. But that’s not all… The real value here is not so much this one agent that is currently in phase 2. It’s $ELTX’s platform: the patented technology that allows for the development of a whole array of vaccines to be delivered into the lymph nodes turning the body’s own immune system into a vaccine producing factory. So $ELTX is not just a one-song dog and pony show. It’s a technology that can be applied over and over to a spectrum of diseases… it’s a monkey wrench vs a screw driver.
To all of this, you now need to add the fact that $ELTX’s vaccine is off the shelf vs $RVMD’s bespoke vaccine that must be engineered each time for each specific patient. This means $ELTX patients don’t have to wait the 3-4 months post chemo to start therapy. With pancreatic cancer, that is an astronomical advantage, and likely a material factor in the longer survival rates that ELTX has already reported.
$RVMD currently has a market cap of ~$30.1B (trading at $150; with ~ 180M shares floating). $ELTX has a market cap of $233M (trading at $11; with ~12.5 M shares floating). That’s a delta of 133x in market cap 14x more shares floating.
In the oncology space, it is not at all unusual for a company to get bought out post phase 2. That’s generally because by the end of phase 2 all toxicity factors have been mostly eliminated, and phase 3 is predominantly a scaled-up trial with thousands more patients than phase 2 to demonstrate the results at scale. This means the therapy is mostly derisked, so big pharma tries to scoop up the company at a discount to gain from the upside. And in oncology, the upside can be astronomical, making it an enticing risk/reward play. For instance, Merck was considering an acquisition of $RVMD @ $20B in the last quarter, a 33% discount on today’s valuation.
There is little doubt that everyone in big pharma is watching $ELTX and waiting for phase 2 results. Given all the factors above re $ELTX vs $RVMD (none of which is lost on big pharma), my own prediction is that they will not even have do a phase 3; or if they do, they won’t do it alone. They will get bought out, or they will raise capital privately at a premium. Even if I’m wrong and they chose to raise ~$300M to fund phase 3, the dilution factor will be ~65%: they will have to sell ~ 17M shares at today’s valuation to fund phase 3.
Dilution scenario: there is no way that $ELTX will simply dump 17M share on the market in a short period of time to raise the funds for phase 3. This will happen over time and, all things being equal, the stock price will also go up over time and thus reduce the need to sell as many shares.
Private raise scenario: in this scenario, they may well raise ~$300M quickly, but those shares will trade off the market so there will be no risk of over supply that could tank the price.
Acquisition scenario: I’m my opinion, this is the most likely scenario… if the board doesn’t get greedy. Given the $ELTX vs $RVMD analysis, I think $10-$12B is a bargain price for $ELTX. That’s a 50-60x upside from today. I can’t imagine the board would say no to such an offer if they get it, only to hold out 3-4 years longer with uncertainty to get more post phase 3. A $10-$12B deal has the potential to change the lives of every single investor in the company, including all the employees.
But hey… what do I know.
Khoopy ELTX 8 months ago #5$ELTX The news from the meeting was very promising! They have data showing antigen spreading (non-KRAS) response across diverse HLA types at 87% (13/15).
This means that 87% of the patients analyzed so far in the phase 2 trial are showing T-cell activity against biomarkers that were not even included in the vaccine!
That means their immune system is aggressively finding new biomarkers as the T-cells kill the tumor cells and then expand the library of biomarkers on the fly.
This is jaw-dropping information. $ELTX seems to have found a way to educate the immune system in ways previously unimaginable. This all may well be why Merk pulled out of the $RVMD deal, fully realizing that $ELTX is simply a much better acquisition target. Their technology can be applied to a broad range of targets. Their vaccine is off the shelf. And it’s spromising to be the gift that keeps on giving as previously unmarked biomarkers get found and targeted. Call me a dreamer, but it doesn’t strike me as crazy to figure Merk would happily pay the same $30B for $ELTX. It’s simply an all around better acquisition. Here’s hoping they pounce on it the minute phase 2 results are released.
Khoopy ELTX 8 months ago #6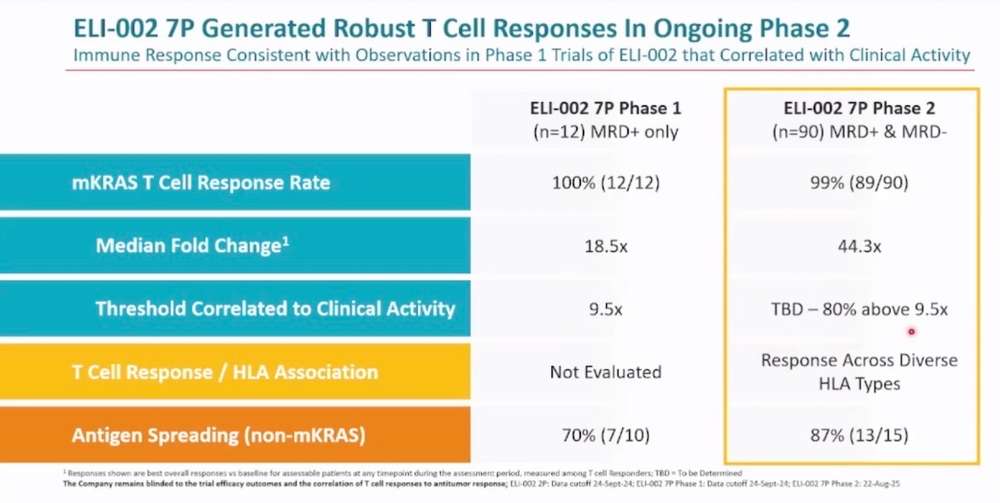
Khoopy ELTX 8 months ago #7$ELTX has a superior product. It’s an off-the shelf product that does not require months of waiting for a specific vaccine. Their vaccine also has a much broader application. Their technology can also be applied to variety of immunology solutions. All around, it’s a much superior acquisition target. So it makes sense that Merk is holding off. If everything continues as it has and the phase 2 results stay in line with all results from previous trials, we could actually be looking at a revolution in medicine with Elicio’s solution. Here’s hoping for great phase 2 results.
Khoopy ELTX 8 months ago #8$ELTX My guess is they’re expecting positive results from Phase 2, and expect to raise cash to fund phase 3. Depending on phase 2 results, they may get bought out at 10-30x current valuation before dilution happens, which would be a great scenario. But who knows. It just seems counterintuitive to raise this much cash without the expectation to fund phase 3. So it’s not a bad sign.