

NVIDIA Corporation NVDA
Regular-session close
Pre-market · Nov 19, 6:15 AM ET
- YTD
- -19.06%
- 1 year
- -19.06%
Discussion (23046)
 Tim K NVDA 1 year ago #6011
$NVDA?And BearTards think they are correct? ?
$NVDA PT raised to $225 from $200 at Oppenheimer
$NVDA PT raised to $235 from $220 at BofA
$NVDA PT raised to $225 from $185 at Bernstein
$NVDA PT raised to $215 from $170 at JPMorgan
$NVDA PT raised to $210 from $190 at Citi
$NVDA PT raised to $230 from $215 at KeyBanc
$NVDA PT raised to $210 from $206 at Morgan Stanley
Tim K NVDA 1 year ago #6012$NVDA? BofA) NVIDIA: Solid Position Amid the Most Attractive Visible Growth Opportunity, Price Objective (PO) Raised to $235
- Ignore China-related noise, focus on ~ $10 EPS potential in CY27
We maintain our Buy rating on NVIDIA (NVDA), our top pick in the sector. NVIDIA holds a solid position with over 80% market share in the fastest-growing and most attractive global AI infrastructure build-out market, backed by an industry-leading free cash flow (FCF) margin of over 45% and a valuation at roughly 1x earnings growth (compared to the S&P 500 and Mag-7 peers trading at more than 2x PEG). While China-related uncertainty remains, the geopolitical hurdles around exports to China—which we fully exclude from our model—are expected to be more than offset by performance in the rest of the world (FY26E sales of ~$200bn). Overall, we raise our FY26/27/28 pro-forma EPS estimates by 6%/7%/11% to $4.45/$6.26/$8.03, respectively. Our forecasts assume annual revenue growth of $30–35% over 2025–27, and considering NVIDIA’s cited “industry 50% growth,” we estimate EPS power of over $10 by 2027 (with potential to reach $15 longer term). In the near term, given shares are up over 35% within the quarter and expectations are elevated, volatility is possible. However, we expect an upward trend to resume as investors revisit NVIDIA’s strong fundamental outlook. We raise our PO from $220 to $235, continuing to apply a 37x FY26E PE multiple, which aligns with the mid-range of NVIDIA’s historical PE band (25x–56x).
Tim K NVDA 1 year ago #6013$NVDA? "Adoption of NVIDIA's robotics full stack platform is growing at rapid rate, over 2 million developers and 1,000-plus hardware software applications and sensor partners taking our platform to market. Leading enterprises across industries have adopted Thor, including Agility Robotics, Amazon Robotics, Boston Dynamics, Caterpillar, Figure, Hexagon, Medtronic and Meta." - Nvidia's CFO
Tim K NVDA 1 year ago #6014$NVDA? "Thor is the most successful robotics and AV computer we've ever created. Thor will power. Our full stack Drive AV software platform is now in production, opening up billions to new revenue opportunities for NVIDIA while improving vehicle safety and autonomy." - Nvidia's CFO
Tim K NVDA 1 year ago #6015$NVDA?Jensen in Networking
NVIDIA's networking: 1gw factory improvement by tens of percent results in $10 billion, $20 billion worth of effective benefit.
"That's the reason why we purchased Mellanox 5.5 years ago. And Spectrum-X, as we mentioned earlier, is now quite a sizable business, and it's only about 1.5 years old. So Spectrum-X is a home run.
All 3 of them are going to be fantastic. NVLink scale up, Spectrum-X and InfiniBand scale out, and then Spectrum-XGS for scale across."
- Jensen
Tim K NVDA 1 year ago #6016$NVDA? Jensen on Rubin:
"Rubin has a lot of great ideas. I'm anxious to tell you, but I can't right now. And I'll save it for GTC to tell you more and more about it.
Rubin, is already in fab. We have 6 new chips that represents the Rubin platform. They have all ticked up at TSMC. Rubin will be our third-generation NVLink rack scale AI supercomputer. And so we expect to have a much more mature and fully scaled up supply chain. Blackwell and Rubin AI factory platforms will be scaling into the $3 trillion to $4 trillion global AI factory build out through the end of the decade."
Tim K NVDA 1 year ago #6017$NVDA? $NVDA demand updates from Jensen during Q2 earnings call
- AI native startup funding surged from $100B last year to $180B this year, with revenues jumping from $2B to $20B ; next year, being 10 times higher than this year, is not inconceivable.
- everything sold out. H100s sold out. H200s are sold out; with hyperscalers renting capacity from other CSPs.
- the CapEx of just the top 4 hyperscalers has doubled in 2 years to $600 billion per year
- we represent about $35 billion plus or minus of that and $35 billion out of $50 billion per gigawatt data center
- China's TAM of $50 billion this year, you would expect it to grow, say, 50% per year. As the rest of the world's AI market is growing as well
Tim K NVDA 1 year ago #6018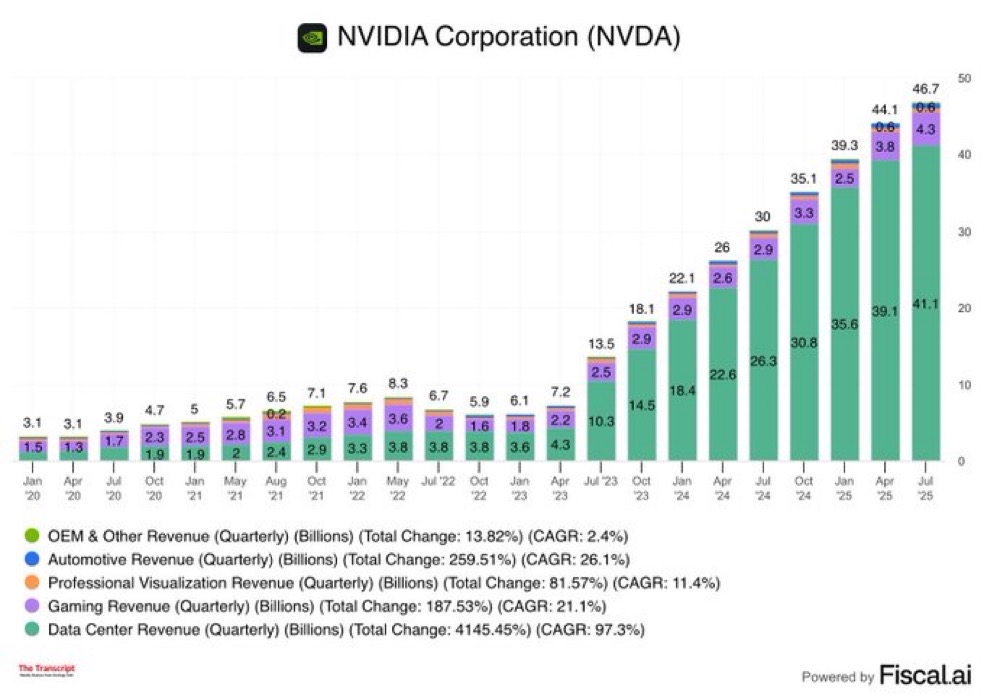
 Nippsy NVDA 1 year ago #6019
Nippsy NVDA 1 year ago #6020billions for buybacks !! Make calls !! Bear trap of the century !!!!!