Menu

Elmar A. Busch

846 posts

Posts (846)

Elmar A. Busch BB 6 days ago #1

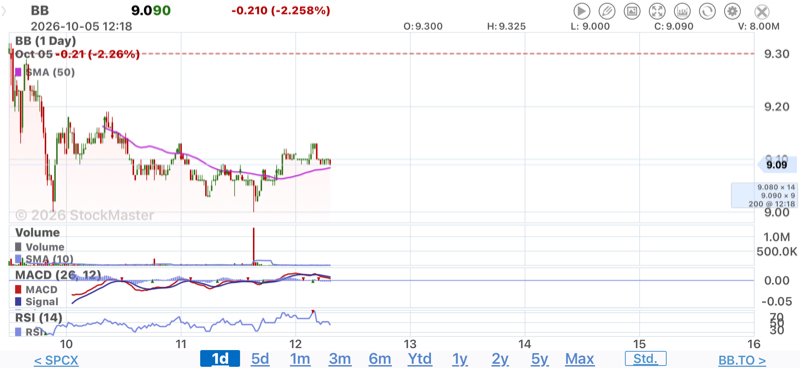
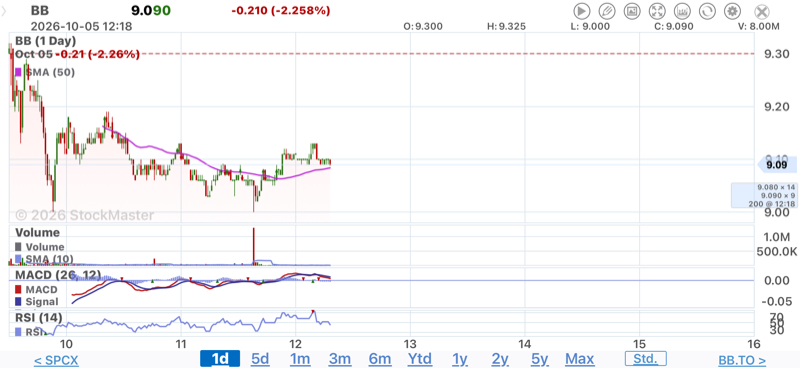
Interesting fact, in today’s market rout 80% of all trades SELL orders, were retail traders, I.e. small investors, small day traders. Institutional investors held back and were active in bottom picking! The emotional fear factor hit the markets!

Elmar A. Busch SPCX 6 days ago #2

Interesting fact, in today’s market rout 80% of all trades SELL orders, were retail traders, I.e. small investors, small day traders. Institutional investors held back and were active in bottom picking! The emotional fear factor hit the markets!

Elmar A. Busch SGQ.V 3 weeks ago #3

Mongolia coal prices (both thermal and coking), and Mongolian exporters such as SGQ are structurally well placed to capture the beginning phenomenal growth path!
Especially Coal price respond positively to global conflict.
Historical precedent is clear. The 2022 Russia-Ukraine war drove sharp spikes in thermal coal prices (gas-to-coal switching in Europe, EU ban on Russian coal, supply disruptions). More recent Middle East tensions have also lifted thermal coal as a gas alternative, though less dramatically. A full-scale European conflict involving Russia would add further pressure via disrupted Russian exports, higher European demand for substitutes, logistics risks (Black Sea etc.), and broader energy-security buying. Coking coal would also benefit from steel-sector demand and any seaborne supply interruptions. China, as the world’s largest coal consumer and importer, would feel the global price lift even if its own production volumes continue. 
Mongolia’s role for China.
In H1 2026 Mongolia supplied 26.5% of China’s total coal imports (second place) and a much larger share of coking coal imports (often 50%+ in recent periods). August 2026 data showed Mongolia overtaking Russia as the largest monthly supplier (9.81 Mt vs 9.20 Mt). January–August 2026 Mongolian exports reached ~77.8 Mt, all to China and up ~47% year-on-year; full-year 2025 was already ~90 Mt. China is deliberately shifting toward more land-based, nearby supply for cost, blending quality, and security reasons, especially amid domestic production curbs . Official discussions and bilateral talks have repeatedly targeted higher Mongolian volumes, with rail capacity expansions (including Shivee Khuren–Ceke) and longer-term goals exceeding 100 Mt+. 
SGQ 1878.HK specifically.
SouthGobi is a direct beneficiary of this channel. Its Ovoot Tolgoi mine sits 40km to the Shivee Khuren–Ceke border crossing. In H1 2026 Sgq sold 6.6 Mt (up from 5.0 Mt) at higher average realized prices ($57.7/t vs $55.4/t), producing a clear operating-profit turnaround ($18.7 million vs a prior-year loss). Q2 alone was 3.5 Mt at $60.6/t. Full-year 2025 had already reached 11.2 Mt and ~$600 million revenue. A sustained rise in Chinese coking and thermal coal prices will flow straight into higher realized prices and EPS for a producer whose product mix includes premium semi-soft coking coal. Volume is also supported by China’s policy tilt toward Mongolia. Q3 exact figures for SGQ will be published Nov. 15th it appears volume for Q3 will approach 4 Million tonnes prices and margins increased in general by over 15 % over Q2.
Overall, the combination of a conflict-driven coal price lift and China’s documented push for more Mongolian supply is further constructive for Mongolian exporters’ earnings.


Elmar A. Busch 1878.HK 3 weeks ago #4

Mongolia coal prices (both thermal and coking), and Mongolian exporters such as SGQ are structurally well placed to capture the beginning phenomenal growth path!
Especially Coal price respond positively to global conflict.
Historical precedent is clear. The 2022 Russia-Ukraine war drove sharp spikes in thermal coal prices (gas-to-coal switching in Europe, EU ban on Russian coal, supply disruptions). More recent Middle East tensions have also lifted thermal coal as a gas alternative, though less dramatically. A full-scale European conflict involving Russia would add further pressure via disrupted Russian exports, higher European demand for substitutes, logistics risks (Black Sea etc.), and broader energy-security buying. Coking coal would also benefit from steel-sector demand and any seaborne supply interruptions. China, as the world’s largest coal consumer and importer, would feel the global price lift even if its own production volumes continue. 
Mongolia’s role for China.
In H1 2026 Mongolia supplied 26.5% of China’s total coal imports (second place) and a much larger share of coking coal imports (often 50%+ in recent periods). August 2026 data showed Mongolia overtaking Russia as the largest monthly supplier (9.81 Mt vs 9.20 Mt). January–August 2026 Mongolian exports reached ~77.8 Mt, all to China and up ~47% year-on-year; full-year 2025 was already ~90 Mt. China is deliberately shifting toward more land-based, nearby supply for cost, blending quality, and security reasons, especially amid domestic production curbs . Official discussions and bilateral talks have repeatedly targeted higher Mongolian volumes, with rail capacity expansions (including Shivee Khuren–Ceke) and longer-term goals exceeding 100 Mt+. 
SGQ 1878.HK specifically.
SouthGobi is a direct beneficiary of this channel. Its Ovoot Tolgoi mine sits 40km to the Shivee Khuren–Ceke border crossing. In H1 2026 Sgq sold 6.6 Mt (up from 5.0 Mt) at higher average realized prices ($57.7/t vs $55.4/t), producing a clear operating-profit turnaround ($18.7 million vs a prior-year loss). Q2 alone was 3.5 Mt at $60.6/t. Full-year 2025 had already reached 11.2 Mt and ~$600 million revenue. A sustained rise in Chinese coking and thermal coal prices will flow straight into higher realized prices and EPS for a producer whose product mix includes premium semi-soft coking coal. Volume is also supported by China’s policy tilt toward Mongolia. Q3 exact figures for SGQ will be published Nov. 15th it appears volume for Q3 will approach 4 Million tonnes prices and margins increased in general by over 15 % over Q2.
Overall, the combination of a conflict-driven coal price lift and China’s documented push for more Mongolian supply is further constructive for Mongolian exporters’ earnings.

Elmar A. Busch BB.TO 1 month ago #7

Someone sold this morning 1.3 million shares in US, that is reason for the dip!

Elmar A. Busch BB 1 month ago #8

Someone sold this morning 1.3 million shares! That is reason for the dip!

Elmar A. Busch BB 1 month ago #9

I simply doubled up at $8.08. The only way to deal with stupidity!

Elmar A. Busch BB.TO 1 month ago #10

The consensus anticipates steady execution matching $0.04 EPS / ~$144M Revenue, with development license revenue offsetting auto production volume dips. An outright guidance raise for next quarter is unlikely to be dramatic, given the macro environment across global car manufacturers.